Field report E-47 / M3 · sheet /deals
M&A & DealsFiled from the territory
Natixis Refinances Manhattan’s Ritz Plaza With $233.3M Loan
CBRE arranged Natixis’s $233.3 million floating-rate refinancing of Manhattan’s 45-story, 439-unit Ritz Plaza. Stonehenge Investment and an undisclosed global investment firm form the borrower.
- Grid
- E-47 / M3
- Surveyed
- November 16, 2026
- Reading
- 3 min read
- Correspondent
- Olivia Hart
Field notes
- Natixis provided a $233.3 million floating-rate loan to refinance The Ritz Plaza.
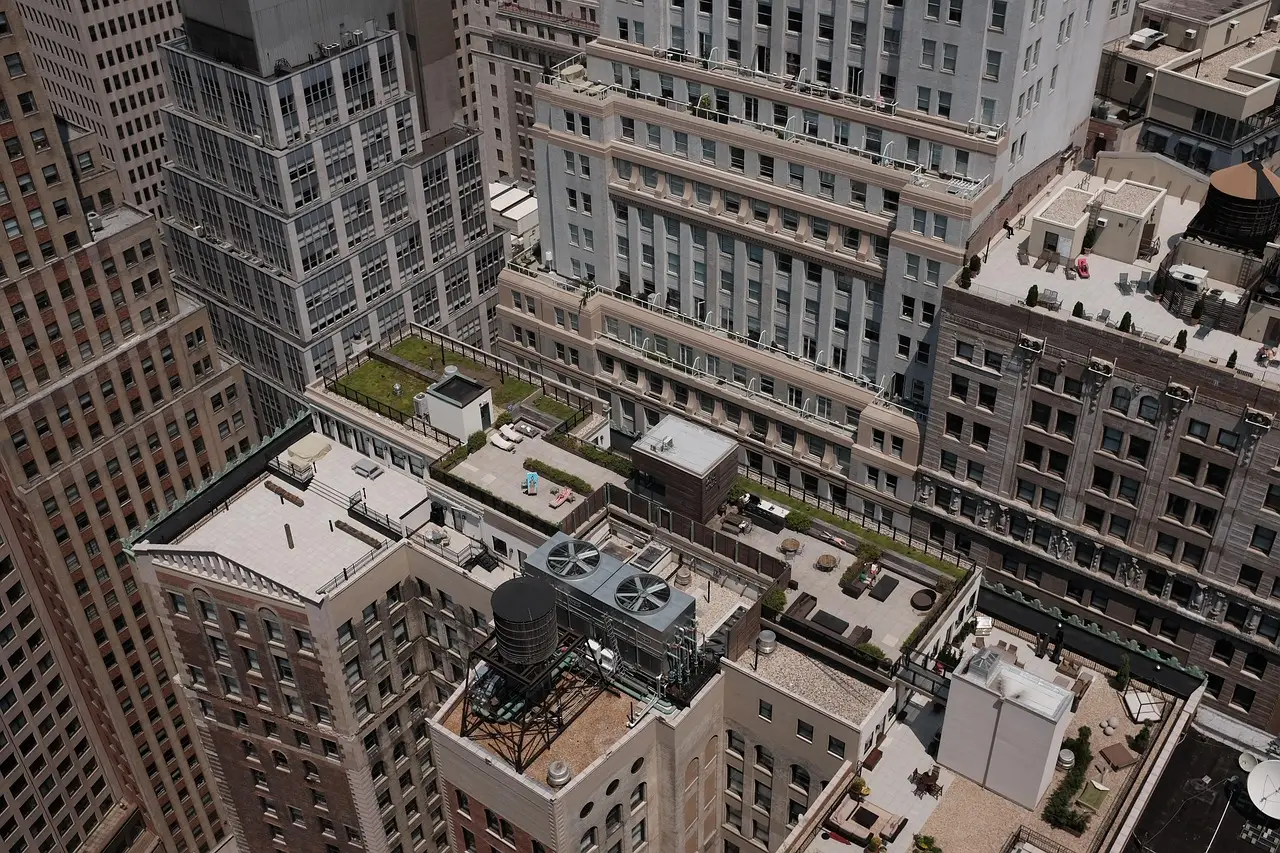
- The 45-story building stands at 235 W. 48th St. in Manhattan’s Midtown West neighborhood.
- Built in 1990, The Ritz Plaza has 439 residential units and ground-floor commercial space.
- Stonehenge Investment and an undisclosed global investment firm form the borrowing joint venture.
- CBRE’s Lawrence Britvan and Michael Straw arranged the loan for the borrower.
By Olivia Hart
Natixis, a French investment bank, has provided a $233.3 million floating-rate loan to refinance The Ritz Plaza, a 45-story apartment building at 235 W. 48th St. in Manhattan’s Midtown West neighborhood. The borrower is a joint venture between Stonehenge Investment and an undisclosed global investment firm. CBRE’s Lawrence Britvan and Michael Straw arranged the financing on the borrower’s behalf.
Who arranged the $233.3 million loan?
Britvan and Straw acted for CBRE as arrangers of the floating-rate loan, while Natixis supplied the debt capital. That division places the lender and the intermediary in distinct roles: Natixis holds the financing exposure, and CBRE connects the borrower with that capital.
The borrower’s joint-venture structure gives Stonehenge Investment a partner without disclosing the other investor’s identity. Readers therefore cannot assign the transaction to a named global institution from the announcement, nor evaluate the undisclosed partner’s funding base or investment objectives.
What does the property contribute?
The Ritz Plaza was built in 1990 and stands 45 stories high at 235 W. 48th St. in Midtown West. Its physical and operating profile includes:
- 439 residential units
- Ground-floor commercial space
- Doorman service
- A fitness center
- A resident lounge
- A rooftop terrace
The combination places residential space above street-level commercial premises in an existing Manhattan asset. The refinancing therefore concerns an established property rather than a new construction project, although the announcement reports no renovation or operating changes.
What does the floating-rate structure change?
A floating-rate loan changes its pricing as the applicable reference rate moves. The announcement identifies the loan as floating-rate but does not name a benchmark, margin, maturity, amortization schedule or prepayment terms.
For the borrower, that structure can leave debt-service costs exposed to rising reference rates. The release does not state whether the joint venture holds rate protection or has otherwise managed that exposure.
For Natixis, the $233.3 million loan creates a financing exposure tied to one Manhattan property. The building’s operating performance and the loan’s pricing therefore matter to credit assessment, although the announcement provides no rent roll, occupancy data, expenses, valuation or debt-service figures.
For the borrowing joint venture, the transaction resembles replacing the funding arrangement on an existing property rather than acquiring a new asset. The move keeps the venture’s capital attached to a building it already finances, though the announcement does not disclose the prior loan or its replacement terms.
Which terms remain undisclosed?
The disclosure covers the lender, loan amount, interest-rate structure, property address and arrangers. It leaves several commercial terms unspecified:
- Closing date
- Benchmark or rate-setting basis
- Margin or spread
- Maturity
- Fees
- Amortization schedule and prepayment terms
Without those figures, the available information cannot establish the loan’s total interest cost, effective yield or annual debt service.
The property details establish scale but not financial performance. Its 439 units, 45 stories, commercial space and service amenities describe the asset; the announcement provides no occupancy, rental income, operating expense or capitalization figures to measure returns.
The 1990 construction date likewise offers no basis for judging current condition or future capital needs. Without a renovation budget or capital expenditure plan, no one can determine whether the refinancing anticipates material building work or simply replaces debt on an operating property.
For practitioners, the immediate fact is the $233.3 million refinancing, not a disclosed change in strategy or operations. The next assessment turns on the missing pricing and maturity terms, and on how the joint venture manages floating-rate exposure within its financing arrangements.
via rebusinessonline.com (Source)
More from Olivia Hart
Show full bio
News editor covering regulation, policy and their impact on corporate strategy and chief-executive leadership at CEO Frontier.
456 articles
Adjacent sheets
- Mesa West Capital Provides $94.2M Henderson Senior Housing Loan
- Affinius Bets $100.3M on Pittsburgh Student Housing Amid 2028 Wait
- BWE Lands $240M Recapitalization for Midwest Seniors Housing Portfolio
- Berkadia Closes $219M Fannie Mae Loan for Manhattan Affordable Housing
- Aline Secures $206m Financing Led by Square Nine Capital