Field report NW-64 / R3 · sheet /macro
Boardroom MacroFiled from the territory
France’s debt and unrest sharpen the US fiscal warning
France’s debt near 120% of GDP, 8.3% unemployment and youth unrest offer a warning to Washington, where debt is about 100% of GDP and the tax wedge is 30%.
- Grid
- NW-64 / R3
- Surveyed
- November 17, 2026
- Reading
- 3 min read
- Correspondent
- Elena Vasquez
Field notes
- France’s report put public debt at 116% of GDP; its headline cited 126%.
- French unemployment was 8.3% in Q2, while real GDP grew 0.4%.
- French wage growth was 1.7%, and 30-year bonds topped 5.4%.
- Long put U.S. debt near 100% of GDP and growth just above 2%, against 120% and 0.5% in France.
- The OECD tax wedge was 47.2% in France and 30% in the U.S.
By Elena Vasquez
France’s public debt stood at 116% of GDP in the report’s detailed data, while its headline cited 126%; French 30-year bonds topped 5.4% at the time of writing.
Heather Long, chief economist at Navy Federal Credit Union, put U.S. debt at about 100% of GDP and described France as further along the debt-crisis curve. At a Bipartisan Policy Center event last week, she contrasted French growth of about 0.5% with U.S. growth just above 2%.
Long said those differences explain why Washington pulled back in recent weeks while France did not. The indicators still give the U.S. room to debate fiscal policy, she said, even within a K-shaped economy.
What does the French unrest reveal?
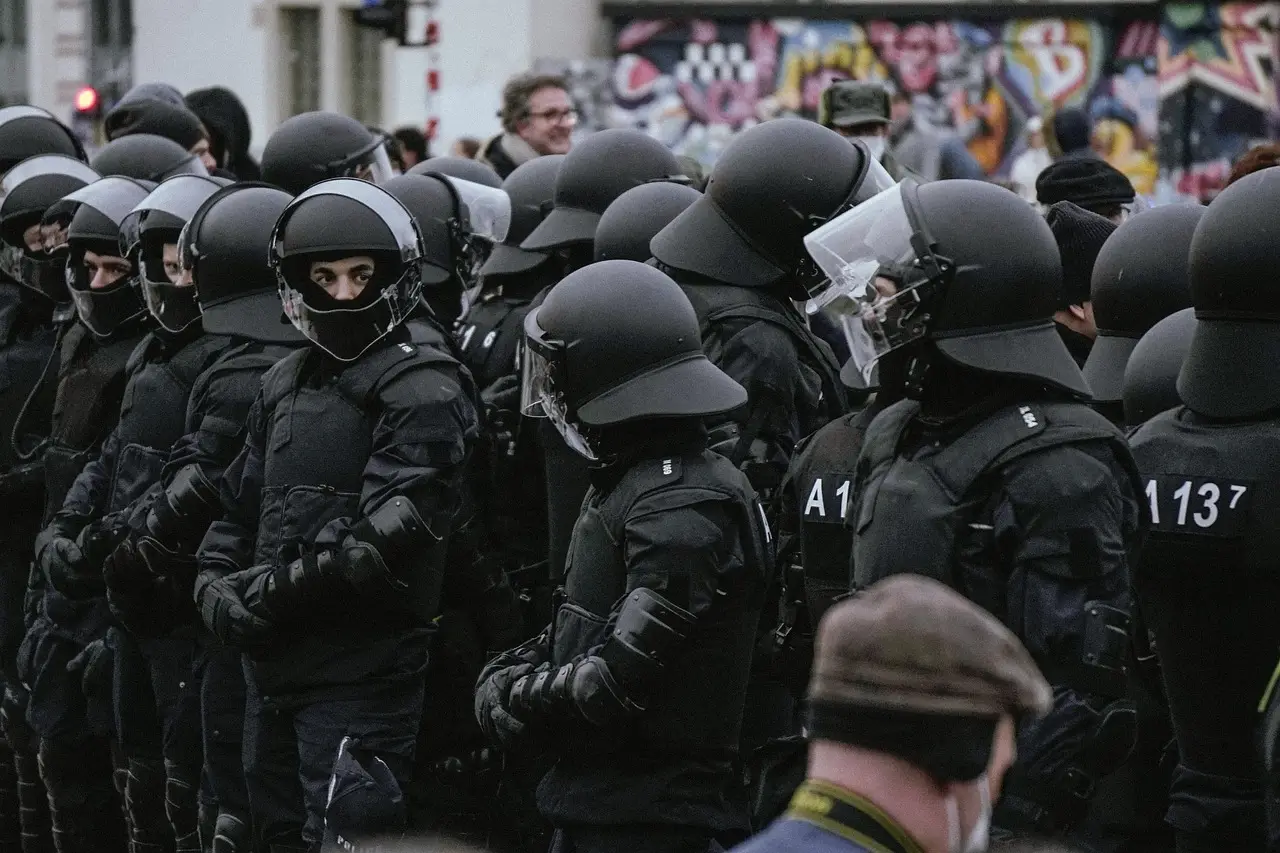
Unrest in Paris began with complaints about the public-school system and widened into protest over the cost of living and job prospects. U.S. markets watched the disorder unfold, with the consensus that Washington should avoid France’s fiscal trajectory.
France’s labor market and economy entered the unrest with:
- Unemployment of 8.3% in Q2.
- Real GDP growth of 0.4%.
- National wage growth of 1.7%.
Those readings show high joblessness and stagnation, leaving French policymakers with less scope to raise growth and reduce the debt burden.
The U.S. bond market offered a contrasting signal. It stalled amid fiscal gridlock over mounting debt, yet 10- and 30-year Treasury yields declined.
How much fiscal room remains?
Long said France has already exhausted much of its revenue-generating capacity through taxes. The OECD’s latest data put the French tax wedge—the difference between an employer’s labor cost and an employee’s net take-home pay—at 47.2%, compared with 30% in the U.S.
She said raising U.S. taxes is not easy, but the country has more room than France to experiment with tax policy and generate growth from a financial-market perspective. Her assessment rested on the U.S. combination of lower debt, faster growth and a smaller tax wedge.
Economists at the event broadly warned that hopes of simply growing the United States out of a debt crisis remain naive. Starting from stronger growth and lower debt than France, however, gives Washington a better chance to rebalance its debt-to-GDP ratio.
Long placed the larger warning beyond the K-shaped economy. She said young people drove the latest protest because they see generational disparities, a dynamic that could become more acute in the U.S. as debt moves toward 120% of GDP. She called it “a pretty big foreshadowing [of] what we could see here as we creep towards 120% debt to GDP.”
Why does timing matter?
Phil Swagel, director of the nonpartisan Congressional Budget Office, framed debt repayment as a question of when, not if. He told the same BPC event that policymakers must decide how to prepare for slower growth if they cut spending and which forms of taxation to explore.
Swagel said: “The longer we wait means some generations, in some sense, don’t share in the burden of the adjustment. Then, who within each generation is affected?”
Swagel said he believes a societal consensus favors a progressive distribution, with households having relatively high lifetime incomes bearing more of the adjustment. He stressed that progressive described a societal preference, not a political position, and said substantial disagreement remains over which generation and which people should bear the burden through taxes.
For Washington, France’s message is narrow but consequential: fiscal choices become harder as debt approaches 120% of GDP, and every delay shifts more of the adjustment across generations.
via fortune.com/feed/ (Source)
More from Elena Vasquez
Show full bio
Staff writer covering companies, deals and strategy in corporate strategy and chief-executive leadership at CEO Frontier.
486 articles
Adjacent sheets
- U.S. Debt Now Equals the Economy; Tax Cuts Added $10 Trillion
- Democrats Sweep Congress Into a $2 Trillion Deficit Reality
- Stock sell-off points to U.S. fiscal risk, not AI debt alone
- Oxford Economics Warns Boom Is Sowing Seeds of a Deeper Recession
- IMF Warns Bond Yields Could Spike as Debt, Inflation and AI Borrowing Surge