Field report S-37 / Q3 · sheet /macro
Boardroom MacroFiled from the territory
Banks Press RBI for Central Fraud Claims System Before 2027 Payouts
Banks have asked RBI for a centralised fraud claims system before January 2027 payouts of up to ₹25,000 begin, citing split liability and mule-account concerns.
- Grid
- S-37 / Q3
- Surveyed
- November 13, 2026
- Reading
- 3 min read
- Correspondent
- Amara Osei
Field notes
- RBI's fraud compensation framework takes effect in January 2027.
- Eligible victims can claim 85 per cent of net loss or ₹25,000, whichever is lower, once per lifetime.
- RBI bears 65 per cent of payouts; domestic customer and beneficiary banks bear 10 per cent each.
- RBI published its digital payments fraud discussion paper in April 2026.
- Banks reported their request via The Economic Times on 13 November 2026.
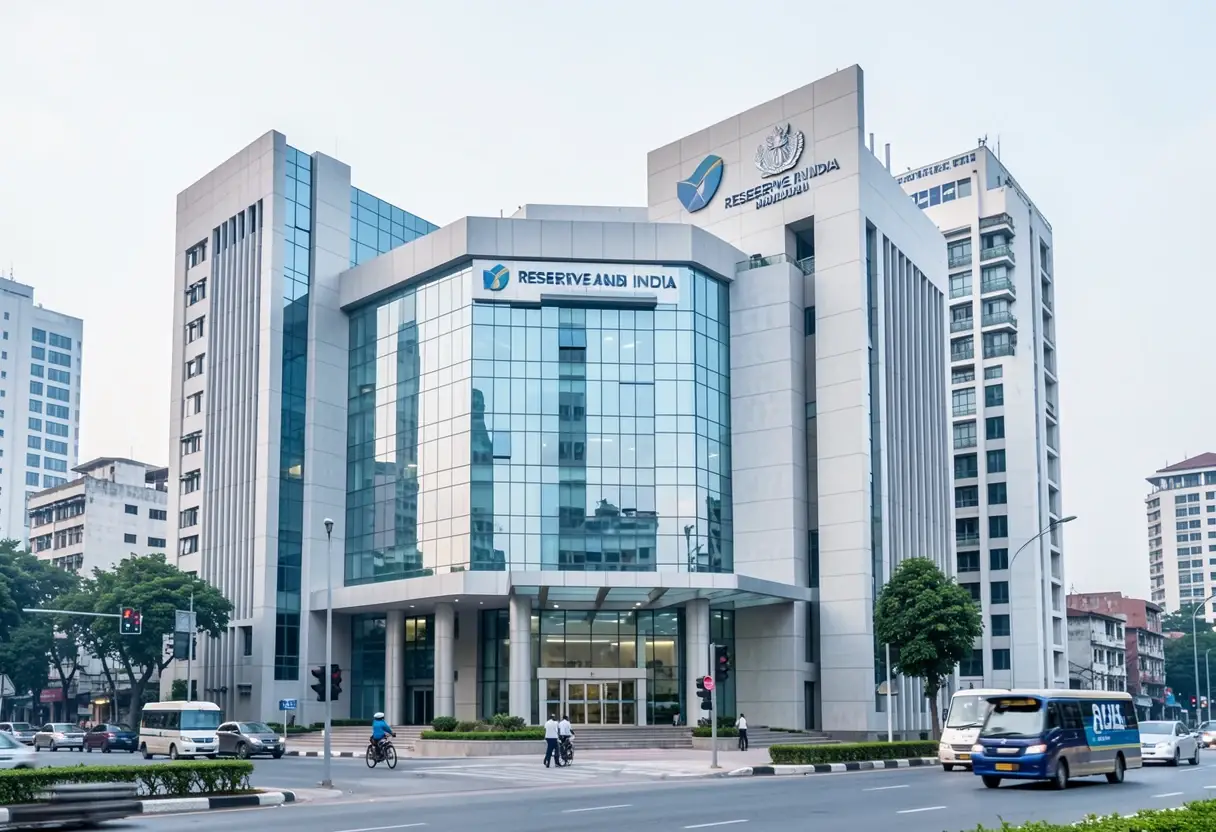
Indian banks have asked the Reserve Bank of India (RBI) to build a centralised, industry-level mechanism for fraud reporting and claim settlement before the regulator's compensation scheme for small-value electronic banking frauds launches in January 2027. The request, reported by The Economic Times on 13 November 2026, seeks clarity on customer eligibility, reporting timelines, beneficiary-bank liability and recoveries.
The scheme will pay eligible victims up to ₹25,000 per claim. It extends a broader RBI framework that already gives UPI fraud victims a route to zero liability.
What does the compensation framework offer?
Under RBI's instructions titled 'Limiting Liability of Customers in Unauthorised Electronic Banking Transactions', an individual acting in good faith who complains of a gross loss of up to ₹50,000 receives 85 per cent of the net loss or ₹25,000, whichever is lower. The payout is computed after deducting recoveries from the gross loss. The benefit is available once in a person's lifetime.
The full provisions appear in RBI's directions for commercial banks on limiting customer liability. The cost of each payout is shared between three parties:
- Domestic fraudulent transactions: RBI bears 65 per cent, the customer's bank 10 per cent and the beneficiary bank (the bank holding the fraudster's account) 10 per cent.
- Cross-border fraudulent transactions: RBI bears 65 per cent and the customer's bank 20 per cent.
- Uncompensated share: the remaining 15 per cent of the net loss stays with the customer.
Why are banks seeking a centralised mechanism?
Bank executives, speaking without being named, said implementation at the level of individual banks could prove difficult and that a standardised industry framework is needed. One executive said suggestions from internal discussions among banks have already gone to RBI.
A second executive said banks support compensation but warned it requires closer coordination among lenders, the regulator and investigating agencies. The executive pointed to ongoing discussions on mule accounts (accounts used to receive and move fraudulent funds), arguing all stakeholders must align on such cases before any compensation is paid.
The concern mirrors the wider debate on bank liability for victims of digital arrest fraud, where the question of who pays has moved to the centre of policy discussions.
How is RBI widening its fraud defences?
In April 2026, RBI released a discussion paper, 'Exploring Safeguards in Digital Payments to Curb Frauds', listing four options:
- Lagged credit for authorised push payments (instant transfers initiated by the payer) other than low-value transactions.
- Additional authentication by a trusted person for high-value digital transactions by vulnerable sections of society.
- Large credits only to accounts that have passed a satisfactory additional review.
- Customer-induced controls on payments.
These measures sit alongside industry efforts, including anti-scam partnerships that banks are forming as AI-driven fraud rises. RBI has also tightened controls elsewhere, such as API safeguards (security rules for software interfaces connecting systems) for bank-NBFC fund transfers.
What happens before January 2027?
Banks want the industry-level reporting and settlement system in place before the framework takes effect in January 2027. The unresolved questions concern eligibility rules, timelines and liability allocation between the customer's bank and the beneficiary bank. Until RBI responds to the lenders' proposals, the operational mechanics of the payouts remain undefined.
Key takeaways
- Banks want an industry-level system for fraud reporting and claim settlement before RBI's compensation framework starts in January 2027.
- Eligible victims with a gross loss of up to ₹50,000 can receive 85 per cent of the net loss or ₹25,000, whichever is lower, once in a lifetime.
- RBI bears 65 per cent of the payout, with the customer's bank and, for domestic cases, the beneficiary bank sharing the rest.
via bfsi.eletsonline.com (Source)
More from Amara Osei
Show full bio
Market editor covering people, launches and day-to-day practice in corporate strategy and chief-executive leadership at CEO Frontier.
272 articles
Adjacent sheets
- NPCI notified UPI Vyapaar Saksham on 11 November 2026: a 5% MDR levy recycled into small-merchant incentives
- RBI consolidates domestic cash transfer rules with immediate effect
- CBN Orders Payment Data Stored in Nigeria From January 2027
- Binance's $6.3bn Hack Exposes Europe's Banking Weaknesses
- Binance says it has covered the full $6.3 billion crypto hack